The last time we covered France’s political chaos, the story was a government that collapsed in 14 hours and student protests over school conditions. Since then, the fight has moved from classrooms to the national budget itself, and the stakes have gotten considerably higher. Here is what has actually happened, in order.
1. Nationwide protests turn into riots
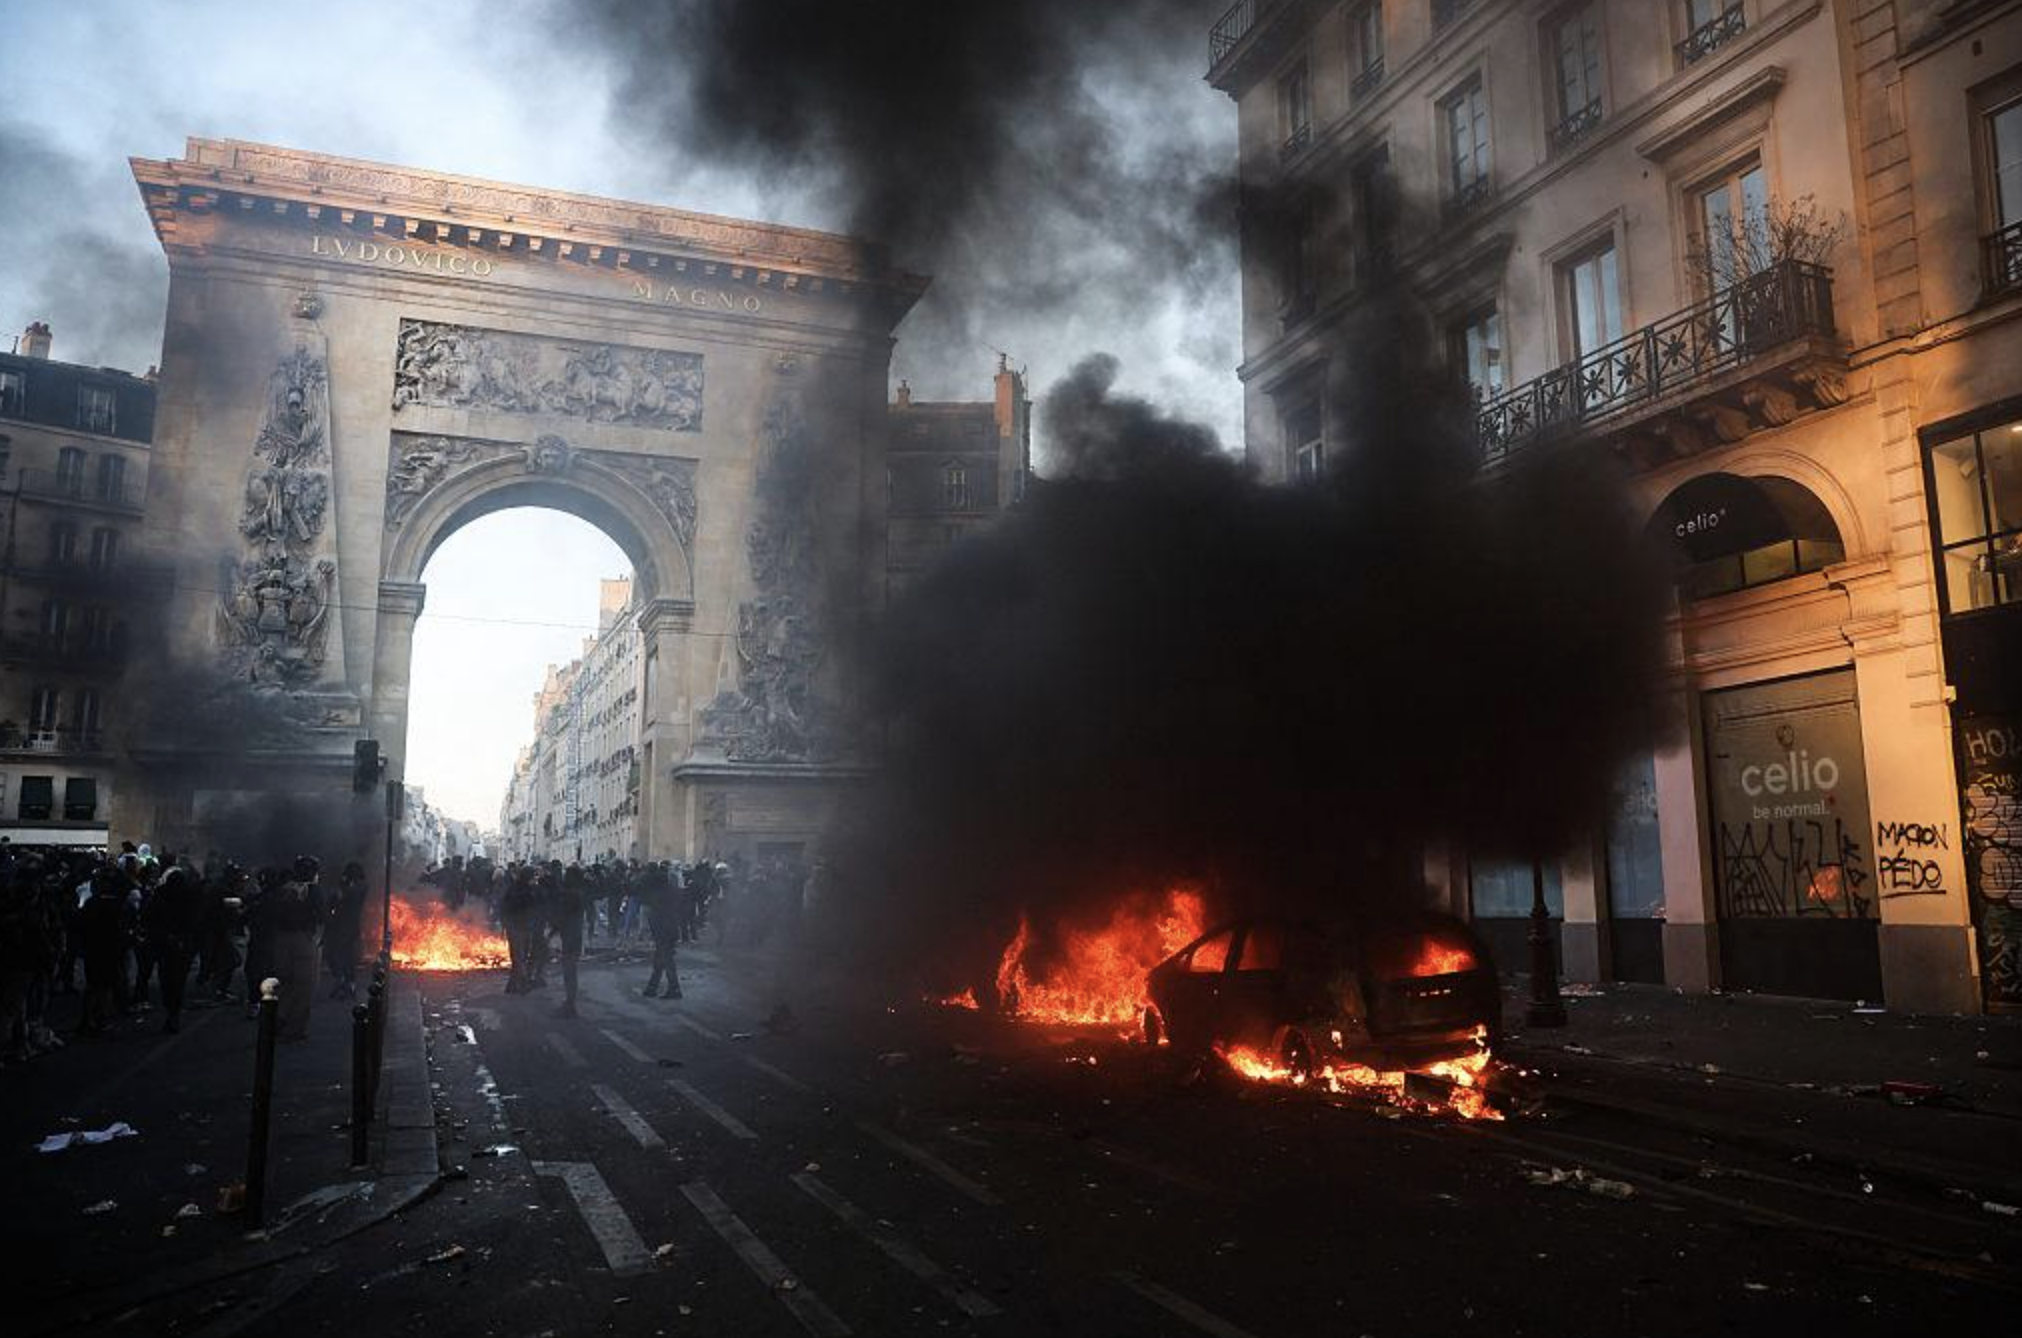
On Saturday, October 17, protests over the cost of living that had been building for weeks turned violent in multiple cities. Looters hit luxury boutiques and supermarkets, and protesters set fire to and defaced public buildings. Authorities deployed 70,000 police officers nationwide, and organizers say more than 500,000 people turned out across the country.
2. Bond markets start pricing in real risk
That same week, yields on French government debt touched 5.14 percent, their highest level since July 2002, while the spread between French and German government bond yields widened to 178 basis points, up from just 85 points in early September and the widest gap in 15 years. Analysts described investors as increasingly worried that France is becoming both socially volatile and politically unable to govern itself.
3. The budget itself goes to a vote
Around October 20, the National Assembly held its first major vote on Prime Minister Sébastien Lecornu’s proposed 2027 budget, a package meant to cut the deficit from 5.4 percent of GDP down to 5 percent. That target sits against a backdrop of public debt that has now reached $4 trillion, or 119 percent of GDP, the highest ratio since the years immediately following World War II.
4. A related bill fails outright
On Friday, October 23, the Assembly rejected the revenue portion of a companion social security financing bill, a real setback for Lecornu’s government. That failure raised the odds of an actual no confidence vote against his government before next year’s presidential election, something that would mean the end of his premiership regardless of what happens with the budget itself.
5. Moody’s declines to pull the trigger, for now
That same Friday, the credit rating agency Moody’s chose not to downgrade France, affirming its Aa3 rating, seven notches above junk and on par with Britain’s, while keeping a negative outlook attached to it. Moody’s cited the same surging bond yields and escalating protests as real risks to the government’s ability to pass its budget at all, and said its baseline assumption is that a deficit cutting budget eventually passes, in its words, “possibly by decree.”
6. The next deadline is already on the calendar
A second ratings agency, S&P, is scheduled to conduct its own review of France on November 27, which gives Lecornu’s government roughly a month to show it can actually get a budget through the Assembly before facing that judgment. S&P and Fitch both already downgraded France once in late 2025, so Moody’s current rating sits one notch above both of theirs.
7. All of it sits on top of an election clock
President Macron cannot run again next year because of France’s two term limit, and the country holds its presidential election in May 2027, followed by a separate legislative election the following month. Far right and far left candidates currently lead early presidential polling, and either outcome could leave France’s next president facing the same kind of fragmented parliament that has made Macron’s final years in office so difficult to govern through.
Why this matters to voters
American budget fights produce government shutdowns, furloughed workers, and a lot of finger pointing, but they do not typically threaten to topple the government itself or move bond markets the way France’s current standoff has. Watching a credit rating agency weigh in on whether a government can actually pass a budget, and watching a failed vote raise the real possibility that a prime minister gets forced out entirely, is a useful reminder that other democracies have built in consequences for legislative gridlock that the American system simply does not have, for better or worse.
References
Fortune, France nears a pivotal moment in its debt crisis amid soaring bond yields and protests
Investing.com, France dodges Moody’s downgrade amid protests and budget gridlock
- France’s Budget Standoff Just Escalated. Here Is How We Got to This Week - October 26, 2026
- A Supreme Court Case You Probably Missed Could Open the Door to a Lot More Election Lawsuits - October 9, 2026
- Dark Money Is Pouring Into the 2026 Midterms. Here Are Five Myths About How It Actually Works - September 21, 2026